

Remember the famous speech by Martin Luther King- “I have a dream”. One of the most profound speeches of all time. This speech is most famous for the articulation of his dream which was the dream of countless Americans. This speech is still the guiding light for people who are fighting for civil liberty and equality all around the world. The beauty of a dream is that they always find an exalted place. There is always an element of impossibility. Has the dream of Martin Luther King been fulfilled after 60 years of that famous speech? Answer is “no”, but American society definitely moved towards that and still finds inspiration to achieve that dream one day. We need to distinguish between dream and goal. Yes, we must have a dream but we must also have clear goals with a clear roadmap to achieve them. Goals have a timeline hence we must maintain a certain discipline to achieve them. Also, we need to assess the feasibility of these goals and accordingly find the resources or trim down those goals. Both dreams and goals fill our life with beauty and colour, provided you are not lost in future. Yes, dreams and goals look as if they are the things of the future and it’s like “I will be happy once I achieve them”. No, the real beauty lies in not losing your “now” and at the same time striving for the future dreams/goals. You are then like an arrow which is determinedly moving towards its target but at the same time enjoying its journey. And it is then, a magical state emerges which is called “Enthusiasm”. Manoj Pandey CFP
Pain of Payment
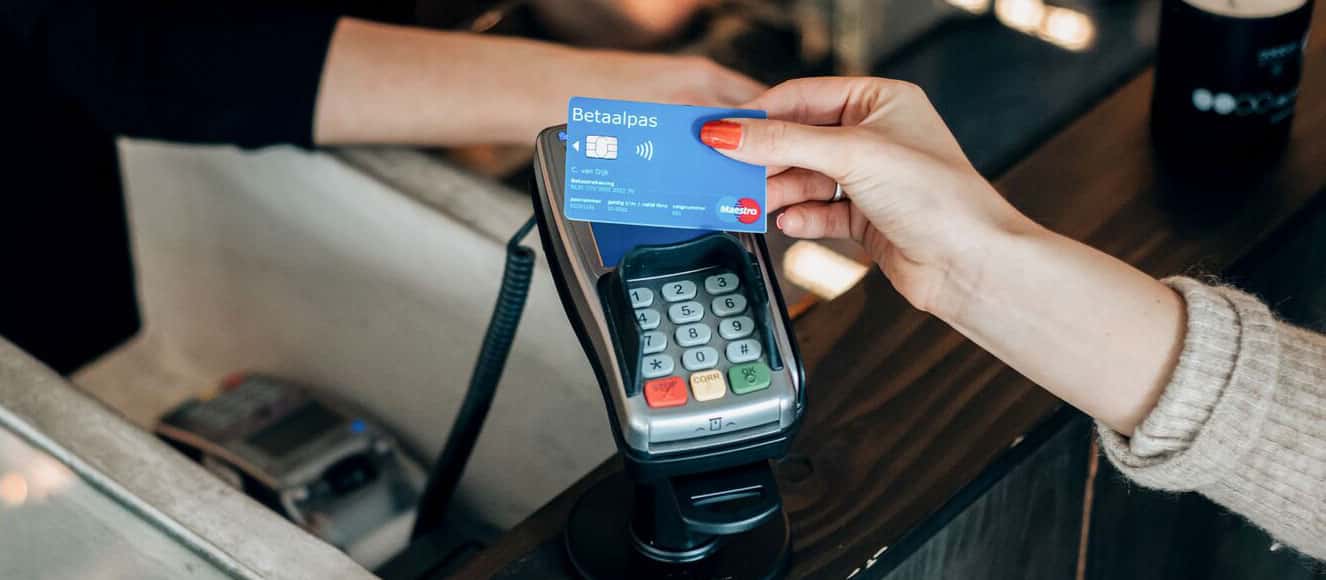
With the advent of so many payment systems making payments has become very easy and smooth. The use of cash is virtually getting extinct. There are the stories of people who have managed with almost no cash during covid lockdown or even during demonetisation. But with all the ease of doing transactions through digital mode, the risk of unconscious spending is on the rise. Making payments has not only become effortless but also sort of pleasurable and this is where I see the problem. Just imagine the situation- you have got the cash from the ATM and plan to use this cash for the next 15 days. So, you would be very diligent in using this cash so that you don’t have to run to the ATM again soon. Every time you have to make a payment, you would evaluate that expense because you have limited cash available which you want to preserve as long as possible. So, for every payment especially if it is non-essential, you feel a certain pain of payment. Every useless expense looks as if someone is robbing you. Thus, your expense would not go haywire. Now come to present times- You don’t need any effort to arrange your purchasing power. All you need is a mobile and a high limit credit card which everyone has and you have the licence to indulge in virtually all the pleasures of the world. As you don’t see the money, you don’t feel the pain of it going out from your bank account or from your credit card. But is this a happy situation for your long-term financial well-being? I don’t think so! My suggestions- 1) Don’t discard the use of cash especially for non-essential expenditures. Pain of payment is good. 2) You will not feel the pain of payments if you don’t see the money. Use this interesting point to your advantage. Invest through SIPs and your investments would become virtually painless. 3) Sometimes you have to do expenses on certain essential items. Use digital payments for good expenses which you must do for your & family’s overall well-being. The bottom line- be conscious while spending and use the pain of payment to your advantage. Manoj Pandey CFP
Is it important to include so many investment avenues?
One of my clients is always very keen to include all the possible investments with the hope that this will make her portfolio well diversified. She insists on investing in Endowment policies, ULIPs, Pension plans, PMS, fixed deposits, mutual funds and in direct stocks. But does investing in all these investments provide sufficient diversification? The answer is emphatic no. This reckless accumulation of investment avenues only increases the cost, complexity and complications. ULIPs, PMS and mutual funds invest in the same investment universe, so including all provides very little diversification. ULIPs and PMS have a higher expense ratio, longer lock-in period, and less transparency than mutual funds, so investing in them just for the perceived (yet incorrect) notion of diversification is not the smartest move. See, the investment avenues are clearly divided into- Equity investments Fixed market investments & Investments in Assets like gold, silver, real estate etc. So, the diversification should be done to include the meaningful representation of these broad categories. For example, if you want to diversify in equity investments, the good diversification is to include large cap funds, multi cap funds, mid cap funds, small cap funds and international funds. On the other hand, taking ULIP plans with the hope that they will complement the mutual fund portfolio and make it more diversified is an example of not so smart diversification. In almost all cases, you can diversify your portfolio efficiently by investing in mutual funds only. Insurance plans are best to cover the insurance only. Mixing insurance with investment is a high cost and long-term lock in proposition, which is best to be avoided. Similarly, PMS are also high-cost plans with a lot of opaqueness and higher tax incidents, thus they are also not worth your salt either. Manoj Pandey CFP
The quality of your questions determines………….
Motivational Guru Anthony Robbins says “The quality of your questions determines the quality of your life”. In the investment parlance, I would like to say ” The quality of your questions determines the quality of your portfolio”. In most of the cases, investors ask these questions- How is the market these days? What do you see the market behave in the near future? Should I invest or wait for correction? Which is the best fund or stock to invest in these days? The correct answers to these questions may not be possible without faking the answer. No one including Warren Buffet and Peter Lynch knows the answers to these questions. Yes, they have admitted it. If you keep asking these questions, your advisor may recommend the incorrect remedy and your portfolio will be doomed to mediocrity. So, what are the right questions to be asked? Here is a list of a few of them- 1) What should be my right asset allocation given my financial goals, risk profile and time horizon of investments? 2) How do you select the right funds? Do you select on the basis of past performance or follow any other criteria? 3) What is the risk management process in your selected list of funds? 4) When do you consider replacing the selected funds? 5) Should I invest the entire amount in one go or is the investment through systematic route preferable? 6) How often would you review my portfolio? 7) What are the fall back options for me if I am not able to achieve my financial goals? These questions not only determine the quality of your portfolio, they may also help you select the right advisor whom you can make the custodian of your hard-earned money. Manoj Pandey CFP
What is the Basic structure of your financial planning?
There is a debate going around the basic structure of our constitution. Except for a few different tunes, the majority of experts believe that the basic structure like supremacy of the constitution, unit and sovereignty of India, democratic and republican form of Government etc should always remain intact. There cannot be any tinkering with the basic structure. Similarly, your financial plan also has a core or basic structure, which should remain intact come what may. Most areas of the financial plan are dynamic and as per the situation, they will continue to evolve or change. But I believe the following core characters should always remain intact- 1) Always follow the fundamentals of investments- Any compromise on these fundamentals due to greed or fear may jeopardise your financial goals. 2) Always follow diversification- Putting all your eggs in one or very few baskets may result in rude surprises. 3) Family first- Ignoring the interest of the family by not taking enough insurance, mediclaim, and not addressing their financial goals would result in huge financial distress not to forget the rift in the family as well. 4) Don’t repent the past- Never beat yourself up about why you have not started the investments early. Any moment is a good moment to start good things. 5) Don’t equate net worth with self-worth- Your self-worth is the result of your feeling of abundance within. It should never be equated with how much money or assets you own. 6) Never stop saving- Irrespective of your income, always make it a point to save some amount. It could be 30%, it could be 10% or it could be just 1% of your income. Amount is less important; the habit of saving is. And the best way to save is not to wait till you finish all your expenses. Save first from income and then manage your expenses with the rest of the amount. These are the few things which should never be compromised in your financial journey. You protect these basic tenets and they will always protect your financial prosperity and peace. Manoj Pandey CFP
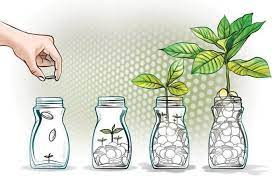
Your Financial Lethargy Could be the Boon for Prosperity
Generally, lethargy is considered as bad. Be active, be decisive, this is what we are advised. But lethargy can be very helpful for investment success. In fact, being overactive is counterproductive. We will discuss that later but first about lethargy. Taking investment decisions always looks difficult and challenging. Where should I invest? Is this a good time to invest or should I wait? Which is a good fund or stock to invest in? Should I believe my advisor or double check with my informed friend? So, it becomes quite a stressful situation and to avoid being in such a predicament, many investors simply prefer to keep the money in bank accounts or fixed deposits where returns don’t even cover the inflation. Yes, making investment decisions for your own money is always nerve wracking. But you can devise a system of bypassing this stress and in turn benefitting through it. You must have heard of the benefits of Systematic Investment Plan (SIP). Yes, you get the advantage of rupee cost averaging, yes, it helps in compulsory saving and yes, your small savings turn into a big portfolio in the long term. But more than that, you relieve yourself the pain of taking investment decisions again and again. You commit once and then investments continue regularly. SIP saves you making unnecessary calculations of market timing, where to invest, which is the right fund etc. Also, once you start your SIPs, generally you don’t stop because again it takes some effort. So, in a way, you have converted your inaction as your investment friend and this is great for your long-term wealth creation. Manoj Pandey CFP
Have a Buddy
Out of those who join Gym, just 10% continue after a couple of months. This ratio increases manyfold if they have a gym buddy. The buddy would continuously pressurise you, persuade you and make the gym visit, a task that must be done. Soon, going to the gym together becomes a fun game. That’s the power of having a buddy. Same thing applies to having a financial assistant or advisor. Even if you know everything about the investments, this person will keep you on your toes to continue your SIPs, keep you motivated during tough markets & continuously remind you about the goals which must be accomplished. This is lacking when you do it all yourself. There is an advertisement in the “Mutual Fund Sahi Hai ” campaign where a gym guy says that he doesn’t need a trainer because he has the knowledge of exercise so he can do it himself. But what is missing in this advertisement is that he had a friend with whom he can discuss his gym prowess, the one who motivates him as well. Which is what you need as an investor to discuss and remain interested in your investment journey. So, be it your investment advisor, or be it your friend. There must be someone with whom you can discuss your investment progress and progress of your financial goals. One who can keep you enthusiastic even in the tough market times. Yes, by investing directly, you may save some commission/fee but you might lose the discipline of continuing a long investment journey which may result in achieving sub optimal outcomes. Manoj Pandey CFP
How frequently you should review your portfolio-
Mostly, there are two sets of investors. One who forgets their portfolio till someone asks them to review it and the other who always cling to their portfolio and keep wondering whether funds need changes. What should be the right strategy? The right thing is to do it in such a way that you can monitor the dynamic situations like- 1) The nature of your financial goals. 2) Your changing risk profile. Or, external factors such as- 1) Whether funds are performing consistently. 2) Whether the fund management team is sticking to the basics. 3) Macro Economic factors affecting the market dynamics. These factors need monitoring but not very often. Frequent churning of the portfolio is counterproductive. You end up replacing the funds based on recent performance which is one of the worst ways of investments. Also, this approach squeezes out some wealth in the form of taxation and exit loads. But not reviewing it is also not conducive either. You may lose out by not taking corrective action based on ever dynamic internal and external factors. Also, by ignoring your portfolio, you may not be able to save enough to achieve your financial goals. So even if you have generated handsome returns on your existing portfolio, you would be far off from your financial goals. So, what should be the ideal frequency? For majority of the investors in majority of the situations, review of financial plan and portfolio, once in a year is good enough. There could be few exceptional situations, which demand more frequent attention. But even in most of those situations, the desired action is to maintain the status quo. Manoj Pandey CFP
Magic of Single Focused Goal-
When Australia made 434 runs in a 50 over match against South Africa, it was thought that the result of the match was a foregone conclusion. It was a world record score already by a distant margin. Additionally, team batting second would have been inundated by the pressure of such a super heavy score. But South African batsmen decided to focus on one ball at a time rather than thinking about the entire target. The basic belief was that if Australia can, why can’t we? With this basic belief and strictly focusing on one ball at a time, things started happening. And what was thought impossible, finally happened. South Africa won the match. When people do their financial planning, they are faced with many enormous targets. How can I generate a corpus of Rs 15 Crores for retirement? Would my children’s’ dream of a foreign college education materialise? How can I achieve my dream home? And then some more. Worrying about all these long-term goals overwhelms them. They either give up on these goals sooner or become desperate. Patience makes way for frustration and haste. But the better way is to focus on one ball at a time. Yes, choosing one decision and sticking with that, come what may… This decision is-focus on your savings. Yes, all you need to do is to ensure that you are saving the requisite amount on a month-on-month basis. You may need to do some adjustment, may need to become more conscious in terms of your monetary habits. Further, you may have to accelerate your saving target progressively the way a smart cricketer builds his/her inning and then up the run rate. You will find that miracles do happen by focusing on one decision rather than keep yourself fluctuating. Further, by focusing on the present rather than worrying about the future, you get true joy of life. After all, life is NOW. Manoj Pandey CFP
Set Goal to Succeed in Financial Planning
When we meet many of our clients and suggest they set their important financial goals, most of them become clueless. So that’s the issue with our relationship with money. We want to become rich; we want to earn a big return; we want to brag about our portfolio but fail to plan the specifics. No wonder whether your portfolio does well or behave miserably, we remain confused. Should we remain invested, book the profit, invest more or altogether get out of the market? Now, we have altered our communication and start asking- Have you planned for your retirement? Have you planned for your children college education? Do you love travelling and if yes, do you plan it in advance so that it won’t affect your entire budget? Do you have enough funds for any emergency situations so that you don’t have to break your investments? And so on…. It makes a huge difference to your portfolio performance if you set financial goals which are very close to your heart and imminent for your family. This also helps you set the right asset allocation depending upon the nature of your goal, time horizon and alternate arrangements. Even if you don’t think about any particular goal, at least start with the goal of “Attaining My Financial Freedom”. Simply stating “I want to earn best return without risking my capital” is not enough. Manoj Pandey CFP
